
The words get used interchangeably, but there's a real difference: a digital wallet is the whole system for storing payment credentials, while a mobile wallet is that system living on your phone with tap-to-pay built in. Which one fits you depends on where you actually pay — desktop checkouts, shop counters, or both.
Quick Answer: A digital wallet stores payment methods across any device (PayPal is the classic example). A mobile wallet — Apple Pay, Google Pay, PhonePe — lives on your phone and uses NFC or QR to pay in person. All mobile wallets are digital wallets; only mobile wallets pay at a tap.
What is a digital wallet?
A digital wallet is software that stores your payment methods — cards, bank accounts, sometimes tickets and IDs — in one encrypted place. The defining trait is that it isn't tied to a phone: log in from a laptop, a tablet or a browser and the wallet is there. PayPal works this way, and so do bank web wallets and platforms like Skrill.
In India, UPI apps added a twist: your "wallet" is your bank account itself, addressed by a UPI ID. PhonePe and Google Pay are technically mobile apps, but the underlying UPI rail works from any participating app or bank.
Used for: online checkouts, peer-to-peer transfers, storing cards you use across devices.
What is a mobile wallet?
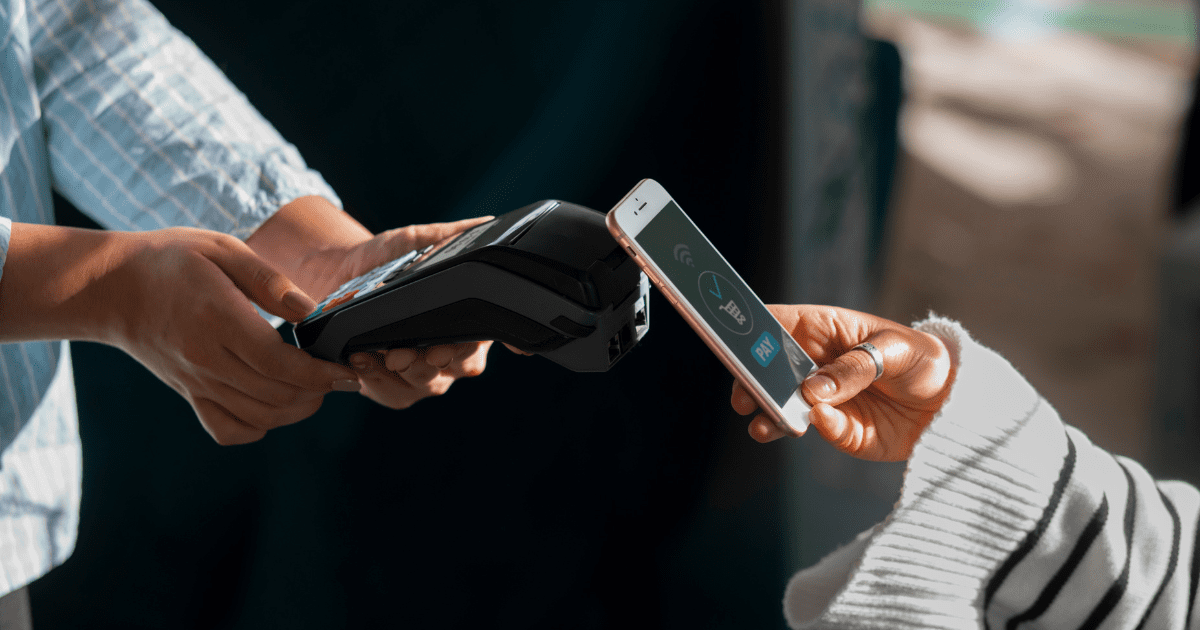
A mobile wallet is a digital wallet designed around a phone — see Investopedia's definition for the formal version. It stores your cards in the device's secure element (or equivalent hardware), wakes up for NFC tap-to-pay at shop counters, shows QR codes where scanners are used, and often unlocks with the phone's own fingerprint or face check. Apple Pay and Google Pay are the global standards; in India, PhonePe and Paytm QR payments dominate shop counters.
The practical difference shows up at the till: a digital wallet on your laptop can't pay a shopkeeper, but your phone can — and since most banks now support tap-to-pay through their own apps too, the phone has quietly become the primary payment device for hundreds of millions of people.
Digital vs mobile wallets, side by side
| Digital wallet | Mobile wallet | |
|---|---|---|
| Lives on | Any device — desktop, tablet, phone | Phone (or watch) only |
| Pay in a shop | Rarely (QR or browser workarounds) | Yes — NFC tap or QR |
| Pay online | Yes | Yes, via app or in-app browser |
| Device security | Password, 2FA | Fingerprint/face + secure element |
| Examples | PayPal, Skrill, bank web portals | Apple Pay, Google Pay, PhonePe, Paytm |
| Best for | Managing cards, online purchases | Everyday in-person payments |
What people actually use them for
- Online purchases — either type fills checkout forms; many shops now accept wallet balances directly.
- In-store payments — mobile wallets via tap-to-pay or QR; this is where the two differ most.
- Peer-to-peer transfers — splitting a bill, paying rent, reimbursing a friend. UPI made this instant and free in India; PayPal and Venmo hold the same role elsewhere.
- Tickets, loyalty cards and coupons — boarding passes and reward cards live in the same wallet app, which is part of why people stopped carrying physical cards.
Choosing between them: what matters
1. Where you pay. If you buy online mostly, a digital wallet alone covers you. If you pay at shops, you want a mobile wallet with tap-to-pay.
2. Which cards and banks you use. Check the wallet supports your actual bank and card network before migrating everything.
3. Security features. Look for tokenization (the merchant never sees your real card number), biometric unlock, and the ability to remote-wipe a lost phone. Mobile wallets are generally harder to misuse than a stolen physical card.
4. Fees. Domestic person-to-person payments are free on UPI; international transfers and currency conversion are where wallet fees hide. Read the transfer page, not the marketing.
5. Acceptance where you shop. The best wallet is the one your regular stores take. In Indian cities that's usually UPI QR; in the US and Europe, NFC terminals.
Which one is right for you?
For most people in 2026 the answer is "a mobile wallet, with a digital wallet behind it." Set up Apple Pay, Google Pay or your UPI app for the shop counter, keep PayPal or your bank's wallet for online purchases and card storage, and you're covered everywhere. I haven't carried more than one card as a backup since I switched to tap-to-pay for daily spending — the wallet app handles the rest.
The real division isn't digital-vs-mobile anymore; it's wallet-plus-UPI in India versus card-tap wallets abroad. Pick from that reality, not from a 2019 comparison chart.
FAQ
Is Apple Pay a digital wallet or a mobile wallet?
A mobile wallet — it's the phone-bound version of a digital wallet, using NFC tap-to-pay and device biometrics. The stored cards inside it are the digital-wallet part. Apple Pay works in shops, in apps and in Safari on the web, which blurs the line further.
Are digital wallets safe to use?
Reputable ones, yes. They encrypt stored credentials, tokenize card numbers so merchants never see them, and add 2FA or biometric checks. A compromised wallet app is recoverable — you change the password and re-secure the device — unlike a stolen physical card, which is why many banks treat wallet payments as the safer option.
Do I need internet to pay with a mobile wallet?
Often not. NFC tap-to-pay on Apple Pay and Google Pay works offline for small amounts because the card token lives on the device; UPI QR payments need a data connection to confirm with the bank. Recharge routes (cached QR, offline UPI via *99#) exist in India for patchy-network areas.
What's the difference between a wallet and UPI?
UPI is the payment rail — the plumbing that moves money between bank accounts instantly. PhonePe, Google Pay and Paytm are wallets/apps that ride on it. Your "digital wallet" in India is largely a friendly interface over UPI plus stored cards.